The Indian infrastructure (construction) and real estate industry is playing key role in the nation’s progress towards achieving the status of ‘developed nation’ from a ‘developing nation’. However, there is a consensus that infrastructure inadequacies would constitute a significant constraint in realizing our growth potential.
An ambitious program of infrastructure investment has therefore been evolved for strengthening and consolidating recent infrastructure and real estate related initiatives. To supplement the estimates of Gross Capital Formation in infrastructure, the Planning Commission has made projections of public-private investments in each sector, basing these on a detailed review of sectoral trends and projected expenditures.
The Indian real estate sector plays a significant role in the country’s economy, which is second only to agriculture in terms of employment generation and contributes heavily towards the gross domestic product (GDP). About five per cent of the country’s GDP is contributed to by the housing sector.
Almost 80 per cent of real estate developed in India is residential space, the rest comprising offices, shopping malls, hotels, and hospitals. According to the Tenth Five-Year-Plan, there was a shortage of 22.4 million dwelling units. Thus, over the next 10 to 15 years, 80 to 90 million housing dwelling units will have to be constructed, with a majority of them catering to middle- and lower-income groups.
Easing the entire cumbersome process of buying or renting a property nowadays, the concept of the development of various online portals for the same has been in recent fashion.
Earlier it was strenuous to search for brokers and agents to rent or buy a home, visit the properties physically, clinching on to the owners for cheaper rents and prices, but now all of these problems have a single solution.
The real estate websites have been an advantage as they provide easy online revival of properties; have unique filters that help the customers to select their preferences and view properties that please them. Accurate pricing, location, amenities, land area, etc provided by these best property sites have made them a recent hit amongst the public.
Apart from all this, these portals have reduced the laborious process of finding and communicating to the owners and agents, a task worth a few clicks
99 Acres
99 acres is an online portal which has been a premier choice of the real estate agents, brokers as well as the homeseekers.
A business venture of the Infoedge group, the purpose of the website is to act as a link between the home buyers and tenants to agents and help them score relevant information about the properties available for rent or for buying around them.
The portal has been expanding rapidly and has already marked its presence in 25+ cities in India. It has earned itself a valid reputation, becoming the 2nd largest property portal in India. The Alexa ranking of the website is 140.
The website was discovered and run since 2005 and recently, they enabled mobile-friendly interface of the portal which allowed their customers as well the brokers to view, exchange information online through the use of cell phones on both android and IOs platforms.
MagicBricks
The game changer in the field of real estate, MagicBricks in number 1 ranked home hunt portal in India. The Alexa ranking of the website is 154. The website is an online business venture of the Times Internet Limited, which is a sub arterial branch of Bennett, Coleman & Co. Ltd.
It works as a two-way portal as it allows both the owners and property agents to list their properties for exposure to the home buyers. The portal has its presence all over India and thus, caters a vast audience.
Apart from providing the mainstream services, the portal also deals with providing relevant information regarding the property related problems generally faced by the people.
The portal also extends its services to the latest property related updates, home loans and taxation information, and also expert advice to its buyers regarding their property related issues. The biggest benefit that they provided to their users is that the users are free to choose properties that are listed by owners to skip the brokerage fee.
The website was earlier computer supported but enabled mobile-friendly interface since the year 2011.
Commonfloor
Having a vast presence in almost 200 cities of India, Commonfloor is an online portal catering to the property buyers and sellers.
The website was discovered first in the year 2007, and now it has more than 5 lakh properties as well as 1000+ upcoming projects registered on the platform. The website has been ranked 210 by Alexa.
The website initially provided real estate management services to its clients, and now they also deal with articles and blogs related to property related topics and issues.
Impact of COVID-19 and lockdown
The business ran as usual for the first two months of the year 2020, but all real estate activities came to a sudden halt in late March with the lockdown. Although the economy started to unlock from June onwards, the situation remained grim through September as construction activities were stalled because of labour paucity, while sales were down on account of concerns over economic growth. The threat of job losses loomed large, which had a major dampening effect on consumer sentiment.
With no site visits possible during the lockdown, real estate developers and property brokers swiftly adopted digital technologies to launch new projects and market their properties, with a fair amount of success. As a positive, the pandemic accelerated the pace of digital adoption in real estate, which will go a long way in transforming how properties are sold in the country going forward. Hence in spite of the situation going down no matter the industry pulled to its socks right on time and ran with the pace of aiming profits and its gross revenue.
The market growth and value
The Construction industry in value terms is expected to record a CAGR of 15.7% to reach $ 738.5 billion by 2022. The Construction industry in India consists of the Real estate as well as the urban development segment. The Real estate segment covers residential, office, retail, hotels and leisure parks, amongst others. While urban development segment broadly consists of sub-segments such as water supply, Sanitation, Urban transport, Schools, and Healthcare. Indian real estate attracted $5 billion in institutional investments in 2020.
• By 2025, Construction market in India is expected to emerge as the third largest globally
• By 2025, Construction output is expected to grow on average by 7.1% each year
• By 2020, Construction equipment industry’s revenue is estimated to reach $ 5 billion
100% FDI under automatic route is permitted in completed projects for operations and management of townships, malls/shopping complexes, and business constructions.
100% FDI is allowed under the automatic route for urban infrastructures such as urban transport, water supply and sewerage and sewage treatment.
Real estate is a field wherein aspiring entrepreneurs can find many paths to success. Many of today’s wealthiest individuals have made their fortunes in real estate, and it’s one of the few business sectors that can deliver fast turnarounds and establish lucrative careers quickly. That said, if you’re getting into real estate to get rich quick, you might need to get real about both your expectations of success and how you’re going to get there.
If you have a passion for real estate, and you are considering making it a business, it can be a rewarding career, if you’re willing to put in the hard work. These hints can help any budding real estate mogul enter the field armed with the insight they need to avoid pitfalls and optimize their paths to success.
The bottom line
The Securities and Exchange Board of India (SEBI) has given its approval for the Real Estate Investment Trust (REIT) platform, which allows all kind of investors to invest in the Indian real estate market. It would create an opportunity worth Rs. 1.25 trillion (US$ 19.65 billion) in the Indian market in the coming years. Responding to an increasingly well-informed consumer base and bearing in mind the aspect of globalization, Indian real estate developers have shifted gears and accepted fresh challenges. The most marked change has been the shift from family owned businesses to that of professionally managed ones. Real estate developers, in meeting the growing need for managing multiple projects across cities, are also investing in centralized processes to source material and organize manpower and hiring qualified professionals in areas like project management, architecture, and engineering.
The residential sector is expected to grow significantly, with the central government aiming to build 20 million affordable houses in urban areas across the country by 2022, under the ambitious Pradhan Mantri Awas Yojana (PMAY) scheme of the Union Ministry of Housing and Urban Affairs. Expected growth in the number of housing units in urban areas will increase the demand for commercial and retail office space.
The current shortage of housing in urban areas is estimated to be ~10 million units. An additional 25 million units of affordable housing are required by 2030 to meet the growth in the country’s urban population.
The growing flow of FDI in Indian real estate is encouraging increased transparency. Developers, in order to attract funding, have revamped their accounting and management systems to meet due diligence standards. Indian real estate is expected to attract a substantial amount of FDI in the next two years, with a US$ 8 billion capital infusion by FY22.
The automobile industry consumes plenty of energy before they ever make it to the open road. Automotive production leaves an enormous footprint because materials like steel, rubber; glass, plastics, paints, and lots of more must be created before a replacement ride is prepared to roll.
Similarly, the top of a car’s life doesn’t mark the top of its environmental impact. Plastics, toxic battery acids, and other products may stay within the environment. Fortunately, junkyard pile-ups are getting much smaller than they were within the past. About three-quarters of today’s average car, including the majority of a steel frame, are often recycled.
Production, recycling, and disposal costs to the environment are difficult to quantify and largely beyond the control of most consumers. It’s also true that the majority of an automobile’s environmental impact, perhaps 80 to 90 percent, are going to be thanks tofuel consumption and emissions of pollutionand greenhouse gases that climate scientists say are driving global warming.
Petroleum products raise environmental red flags even before they’re burned. Extracting them from the world is an energy-intensive process which will damage local ecosystems. Shipping fuels can also consume plenty ofenergy, and creates an occasional environmental disaster like an oil spill. As world demand rises, and unconventional fuel sources, like oil sands, become more economically viable, the ecological impacts of petroleum extraction may additionally increase dramatically. That’s another reason why fuel efficiency is so important.It’s also partly why electric-powered vehicles can help reduce environmental impacts, because the natural resources are not harmed.
The issues are oftendifficult to tease out of other factors, like increaseand resource consumption. And to eradicate such global issues on environment due to the growing of automobile industry the new type of battery based plans has recently been introduced by the Indian government that led to the holistic plan of a roadmap for the future of battery sector with different ministries like power, new and renewable energy, road transport, department of science and technology, heavy industries, external affairs, mining and environment, forest and global climate changeworking in sync as all of them would govern some aspect for the success of the world. With the inevitable growth of Electric Vehicles (EV) and renewable energy sectors, it’simperative for India to forge an ecosystem that permitssetting-up an indigenous battery manufacturing industry. India has been hooked in toexternal imports for oil, solar Photovoltaic (PV) equipment and now even batteries to satisfyits requirements. This makes India vulnerable to becoming hostage to risky supply chains and geopolitical tensions alongsidemammoth capital expenditures. India cannot afford to lose the bus within thebattery sector which is becoming a key for achieving a coffeecarbon economy.
The Electric Vehicle Market is projected to achieve26,951,318 units by 2030 from an estimated 3,269,671 units in 2019, at a CAGR of 21.1% during the forecast period. The base year for the report is 2018, and thusthe forecast period is from 2019 to 2030. The electric vehicles market has witnessed rapid evolution with the continued developments in the automotive sector. Favourable government policies and support in terms of subsidies and grants, tax rebates and other non-financial benefits within the sort of set lane access, and new car registration (specifically in China where ICE engine new car registration are banned in some urban areas) the increasing vehicle range, better availability of charging infrastructure and proactive participation by automotive OEMs would drive the global electric vehicle sales.
The involving and evolving of charging units and battery manufacturers-
The coronavirus pandemic has strengthened the necessity for encouraging domestic manufacturing in India since it’s overly hooked in to imports to suffice its requirements. This has gained urgency since substantial commodities are imported from China, a country, with whom India’s geopolitical tensions is making trade increasingly difficult. With mega targets to build up the renewable energy mix, especially solar, to its power generation capacity, and an increased specialise in electric vehicles (EVs), India has got to make concerted efforts to incentivise the domestic manufacturing of EV components, renewable energy equipment and batteries.
India bought batteries worth USD 1.2 billion in 2019-20 making this sector heavily hooked in to imports. The key sectors which will drive the demand for batteries is that the growth of electricalvehicles (EVs) and renewable electricity storage. EVs are poised to scale back India’s oil import bill and contribute to cleaner air and hence the country has set a target of getting 30 percent EV penetration by 2030. India is additionally tendering many renewable energy plus storage projects where the stationary storage components are going to be catered to by batteries. India lacks the capacity to manufacture cells commercially and, hence, to chopthe coston imports, the Indian government has made plans to indigenise battery manufacturing. A report by NITI Aayog has stated that if India has got to meet its EV targets through one hundred pc domestic manufacturing of batteries, it might require a minimum of 3,500 GWh of battery storage at a wholesale cost of USD 300 billion, which can be but half the value of oil imports thus avoided. The India Energy Storage Alliance (IESA) has estimated a 300 GWh demand till 2025 taking into consideration the EV and energy storage system opportunities. In lieu of the growing battery sector, the Indian government launched the ‘National Mission on Transformative Mobility and Battery Storage’ last year to plugphased manufacturing programmes for battery and EV components. The initiative will support fixing of large-scale export competitive integrated battery manufacturing plants in India. NITI Aayog has proposed fixing gigafactories aggregating a capacity of fifty GWh over subsequent ten years at projected cost of USD 5 billion. The most dominant battery technology today is that thelithium ion (Li-ion) batteries. All the opposite breakthroughs in battery innovation aren’t scalable commercially as of now. Research shows that cost of Li-ion battery packs fell by 85 percent within the last decade and can further fall by 35 percent by 2024 to below USD 100 per kWh. A recent report states that the Li-ion battery manufacturing capacity will grow fourfold to 1.3 TWh in 2030 compared to 2019. Asia Pacific dominates this capacity by accounting for an 80 percent share and, within this region, China, who is that theleader is predictedto double its capacity from 345 GWh to more than 800 GWh by 2030. Rare earth metals like lithium, cobalt, nickel, manganese, etc are the essentialraw materials required to manufacture Li-ion batteries, for which mining of the required metals and fixing of manufacturing plants are highly capital intensive. China has made heavy investments locally and overseas (Latin America, Africa and Australia) in mining lithium and rare-earth elementmetals. Also, China has financed a hugebattery manufacturing capacity making it difficult for other countries to compete.
India has so farnot surveyed if it’s sufficient reserves of lithium. Last year India discovered around 14,000 tonnes of lithium, but this is so oftenoften far less compared to 8.6 million tonnes in Chile, 2.8 million tonnes in Australia and 1.7 million tonnes in Argentina so asto achievebuilding a battery manufacturing industry.
Boldly, India has recently acknowledgedKhanij Bidhesh India Pvt. Ltd. to explore strategic mineral assets abroad. And, India and Australia recently signed a preliminary deal to supply the critical minerals required for a new-energy economy. Though India was late to the solar powerequipment and Li-ion manufacturing race, but it shouldn’t miss the long runbattery technology opportunity. Instead it should explore new approaches by providing for long-term research in multiple aspects of battery manufacturing. These include solid state batteries, battery-chemistries with higher energy densities, new battery materials and chemicals withstanding higher temperatures, hydrogen fuel-cells, etc. If India lays a robustresearch foundation for battery technology, it can use this unique opportunity to steer during asector that interests many economies. India could jump an entiretechnology phase by moving straight to novel battery technologies and strategically reduce its battery import dependence and risks of supply squeeze. Bridging the rift between industry and laboratories can aid faster transitioning towards commercial manufacturing of batteries. The government offersventure funding or high-risk funding to research institutions that specialises in battery technology which shall enable them to showcase the commercialisation potential of their innovations. An example might besodium-ion battery technology whose performance is inching on the brick ofthat of Li-ion batteries and therefore the staplefor these batteries are oftensourced locally leading tolow costs also, As the number of batteries start multiplying, it will cause a bigquestion of battery waste disposal since this willhave serious environmental implications. A report has predicted that by 2030, the battery recycling industry in India are often a million-dollar opportunity. Recycling at an industrial level is completedby EU and China, but the market is at a nascent stage. To scale backimports and attain sustainable battery manufacturing, but looking up to the battery recycling matter is equally important.
There isa requirement for an enabling framework where circular economies of manufacturers undertaking battery recycling or new enterprises that specialize inrecycling develop within the approachingyears. Government of India has renewed its support to the domestic industry to formIndia self-reliant under its ‘Atmanirbhar Bharat’ scheme.
In addition, the growing sensitivity of varied governments toward a cleaner environment has increased the demand for zero-emission vehicles. Developed nations like the US, Germany, and therefore the UK are actively promoting the utilization of electrical vehicles to scale back emissions, which has resulted within the growth of electrical vehicle sales. The electric vehicle market is dominated by globally established players like Tesla (US), BYD (China), BMW (Germany), Volkswagen (Germany), and Nissan (Japan). These companies developed new products, adopted expansion strategies, and undertook collaborations, partnerships, and mergers & acquisitions to gain traction in this high-growth electric vehicle market.
The growth and Scope of Electric Vehicle (EV) market
Moreover, EVs have 75-80% less moving components and this ultimately translate to a way lower maintenance bill. Over and above the robust operating expense angle, EVs also possess an inherent advantage when it involves performance and drive ability. In the last few years, trends suggest an increase in interest among the common masses for electric cars as compared to electric two-wheelers and ICE or petrol/diesel cars, as seen on Google Trends. The manufacturing landscape of EVs, which solely won’t be dominated by the worldwide automakers earlier, is additionally now seeing a reign, as numerous Indian automakers now take a deep dive into the electrical vehicle space, tapping the growing potential that the country has future. India’s push toward electric vehicles are creating opportunities for companies in ancillary spaces like battery manufacturing, consistent with an analyst at diversified financial services firm Motilal Oswal. The move toward electric vehicles is, “inevitable” globally also as in India, where higher fuel prices can make owning cars that run on electricity comparatively cheaper, The acceptability will increase once you have the infrastructure There are two basic sorts of electric vehicles: people who believe batteries and therefore, the hybrid vehicles that use both batteries also as plugging into an external source of power, such as a charging station. What is even more interesting is the mindset of the Indian population is additionally slowly evolving, with many now willing to form a switch to EVs soon. A recent study has highlighted that by 2022, most consumers in India would consider buying an electrical vehicle. This in itself may be a key trend which is probably going to trigger the expansion of the EV segment within the country. Definitely, government intervention and policy has a key role to play in promoting electric mobility within the country. Indian policymakers are actively pushing EV adoption over the recent years, and multiple initiatives have also been introduced to develop domestic capabilities across the whole EV value chain. Besides strengthening the EV manufacturing capabilities, renewable energy targets also are being revisited and various measures are being adopted towards effective recycling of raw materials. The battery price also has been expected to fall by quite 30% between 2018 and 2025, which can make electric vehicles (EVs) cheaper over the amount of your time. Besides this, the government of India has announced various tax cuts and subsidies to further encourage more and more peopled to shop for EVs. The bulk of the thrill in India’s electric vehicle sector is in ancillary spaces where companies are working with global players, many of whom are looking to enter the lucrative market You wear a one hand the battery manufacturers, which are looking to develop the battery for the EVs, and on the opposite side, you’ve got companies like Motherson Sumi, who are into the electrical a part of the vehicles, They are becoming increasing shares of business globally from the (electric vehicle) space. Motilal Oswal prefers Motherson Sumi and Exide Industries, which are up roughly 29% and 11% year thus far as of Monday’s close, respectively. Motherson Sumi works with automakers around the globe in areas like wiring harnesses, rear-view mirrors, cockpits, bumpers and more. Exide sells automotive and industrial lead-acid batteries. Hence, moving to using electric vehicles give businesses the chance to become involved in innovative transport developments which are addressing environmental issues. Setting environmental concerns at the heart of your business can be a key part of demonstrating corporate social responsibility.
The initiative taken by companies on EV in India
It seems that Electric Vehicles (EV) as a thoughtseems to possessfinally come to India. There are many positive green signals coming from the governmentand industry because thenumber of EVs on the road in India has began toincrease. Karnataka are getting tobe home to Tesla’s factory in India, following announcements by Chief Minister BS Yediyurappa and Union Minister for Road Transport and Highways Nitin Gadkari. Investment sentiment has picked up for the planetwith renewed interest by venture capitalists with over US $300 million reportedly invested in companies that affect EVs and better battery technology this year. The number of EVs on the road has also been steadily increasing, and in 2019-20, the amountof EVs on the road stood at 155,400 growing at around 20 percent year-on-year. Government policies just like thatFaster Adoption and Manufacturing of (Hybrid &) Electric Vehicles in India (FAME) which givesubsidies for EV production and charging infrastructure are a welcome fillip. Phase II Clinical trial of the scheme has an outlay of INR 10,000 crore ending this year for creating more demand for EVs. The 2019-20 budget announcements for tax subsidies for loans on EVs are again aimed toward proliferating new kinds ofautomobiles. Broadly, there isa renewed interest by the general publicin owning an EV considering high fuel prices within thecountry, which successivelymakes most goods costlierand contributing to an overall inflation within thecountry.
With these broad signals to the world, there are, however, some policy issues for decision-makers in government, industry, and academia to think about. Like, the Ola Electric on revealed its plans to line up the world’s largest electric two-wheeler charging network. SoftBank-backed Ola Electric plans to providecharging solutions to all or any or any its electric two-wheeler customers. It unveiled the Ola Hypercharger Network, the charging network for its upcoming two-wheeler products starting with the Ola Scooter to be launched within the approaching months. The Ola Hypercharger Network are getting tobe the widest and densest electric two-wheeler charging network within the planet, with quite 100,000 charging points across 400 cities. Within thefirst year alone, Ola is fixing over 5,000 charging points across 100 cities in India, quite double the prevailing charging infrastructure within the country. Ola alongsideits partners would set it up at an estimated cost of $2 billion over a period of 5 years. In India, Ola is now in direct competition with electric two-wheeler makers, like Ather Energy, Hero Electric, and TVS Motor Company. However, the charging network won’t be available to other electric vehicle players and only the purchasers of Ola Electric. And recently, India is also going tocapitalise one of the foremost abundant elements on earth — hydrogen. Minister of FinanceNirmala Sitharman announced the National Hydrogen Mission during the Budget 2021-22 to realizefrom this universally-available element. The green energy source could also compile varietyof India’s biggest companies like Reliance, Tatas, Mahindras, and Indian Oil, the needof the hour could also bea coalition of stakeholders a bit likethe Hydrogen Council or the ecu Hydrogen Coalition. Companies like Indian Oil, the Tatas, the Mahindras, the Eicher — allow them to be an areaof the coalition. Then speciality chemicals companies like Reliance are oftenalso a neighbourhood of it. To be more specific With more and more car manufacturers focusing their efforts on making EVs, it is only a matter of time before there isan EV in every segment and by every major company. The year 2021 will witness the launched of the manyelectric cars and here are five of them The Volvo XC40 was initially introduced within theIndian market with a diesel. Sometime then, the companygot obviate the diesel and brought during a petroleumengine in its place. Now, we’ll be getting a thirdavatar of the XC40 in India and this one are getting tobe all-electric. This one has been eluding us for a couple oftime now. First showcased at the 2020 Auto Expo, the eKUV100 could also be totallyelectric version of the regular KUV100. Another product that was showcased to us at the 2020 Auto Expo was the electrical version of Altroz. The smart-looking hatchback has proven to be a successful product for the home-grown carmaker. It comes with a choice of three engine options currently – 1.2-litre NA petrol, 1.5-litre diesel and thusthe recently launched 1.2-litre turbo-petrol.
The Future of Electric Vehicles (EV)
EVs and therefore the grid can have gigantic synergy. Not exclusively would EVs be ready to charge at whatever point there’s excess force, they need a battery valuable for engrossing variable environment friendly power. They will significantly offer reinforcement power for the lattice. This is often one explanation to make for EVs, one that comes with forceful season-of-day valuing (modest charging when force is excess).
Nonetheless, EVs are efficient—with regenerative braking capturing energy in any case squandered and furthermore due to the characteristic productivity of engines, particularly at low rates—they pollute less. The EVs were designed to guard the environment but thanks to slowdown within the Indian economy, they need now become a requirement in India. There is an unexpected climb within the costs of petroleum and diesel, and pollution levels are gravely high in practically every city of the country.
In such a scenario, EVs seem to be a hope for cleaner future.
There have been enormous changes, especially in technology, but also in individuals’ attitude towards vehicles’ effects on the environment. Although the electrical vehicle market is at the present a rewarding objective for organizations and new businesses in India, there are a couple of obstructions in its production fabricating electric vehicles locally being one among them. Also, battery manufacturing is essentially an upscale endeavour. The Indian Government should focus its energies on checking out these difficulties.
The beauty and wellness industry in India is booming with tremendous potential for growth. In fact, it is said to be growing twice as fast as the markets of the United States and Europe. India is also the second-largest consumer market in the world. India, by contrast, is forecast to grow as a result of strong consumer demand to reach INR 2,463.49 billion by 2024, expanding at a compound annual growth rate (CAGR) of ~18.40% during the 2019-2024 period. Beauty and personal luxury ad spend in India are projected to be 15.2% higher in 2022 than it was in 2019. This includes beauty products, beauty salon and spa businesses. The CAGR of the beauty and wellness business in India has been around 18%. Another prominent feature is that herbal beauty care has driven the growth of the beauty business models in India.
Today, awareness of beauty products and treatments is at an all-time high in India. There is greater awareness of the ingredients in products, and customers make choices based on their increased awareness. This is attributed to exposure to global trends, rising disposable incomes, changing lifestyles, increasing number of women in the workforce and so on.
The retail sector is also booming. No wonder, foreign companies are targeting the Indian market. Many kinds of beauty products for varied purposes are now available based on individual skin and hair type — from sunscreens and moisturizers, to specialized cleansers, face wash, toners, astringents, scrubs, masks, nourishing creams, serums, shampoos, conditioners, hair tonics, hair serums, hair-dressing products as well as cosmetics. It is an ever-growing list. Men’s personal care and anti-ageing products are slated for growth. The retail format is also boosting the growth of the beauty business, with malls becoming popular shopping destinations not only in metros, but also in tier-2 cities. Malls are making shelf space available to beauty brands. An important feature is the tremendous growth of e-commerce, with online stores also becoming popular shopping destinations. The beauty business as a service sector offers great scope for employment and entrepreneurship for women.
The Internet has changed the way we do business. Today, websites are a dynamic system of providing information about your company, the products, and services. Websites increase a product’s visibility and the desire to buy it. This is true of beauty products, where glamour seems to be just a click away. Ever since we started our online portal, the Shahnaz Husain online store has become a popular destination for online shopping.
With the ‘total wellbeing’ concept gaining ground, spa treatments are becoming more popular. There has been an increased need for spa treatments, with salons being converted into day spas, offering both salon and spa treatments. In fact, service industries like spas and Ayurvedic centres are slated for growth. The West is also looking at India’s herbal traditions. My dream is to see India lead the international beauty industry in the next decade.
Till recently, the majority of the beauticians working in the neighbourhood parlours learned the tricks of the trade through the apprenticeship model, without going through a formal training process. They devoted almost six days a week in salons and slogged for 10–12 hours in inadequate working conditions. The business value that beauticians generate for the salons is huge, but it doesn’t translate into profit for the employees. Even salons have to maintain real-estate and other associated costs. So, other than various salons and wellness parlous, some apps like Urban clap and HouseJoy has come up in the business to give the beauty and wellness a better platform like-
UrbanClap has brought together a host of services under one roof where you can rent their service for home cleaning, interior designing and even get beauty services sitting right at your home. Established in 2014, this app was launched for services in Mumbai, Delhi, Chennai, and Bangalore. There are more than 10,000 professionals registered with the platform who are thoroughly verified by the company. The service has really caught on with the busy urban population with their busy life and the company crossed the mark of $10 million in revenue quite recently.2015 based out of Bangalore. Initially, the company was able to raise $4 million in the first round of funding from Matrix Partners. The company was received favourably by the Indian population, who make around 4,000 orders per day, resulting in 30 to 40% weekly growth of the company. Till date, the company has raised $24 million in funding from different investors such as Amazon, Vertex Ventures, and Matrix Partners.
The app for the company was launched in August 2017 and within six months it posted theastonishing figure of profit. Now, it has become one of the fastest growing home servicing start-ups in India and has raised 63 crore INR in funding from Accel India and SAW Partners.
And the other is HouseJoy, and it has also been able to write its success story by having a good business model, managed expenses and costs and efficient management. HouseJoy was able to earn revenues worth $4.72 million in the financial year 2015 – 2016, recording an increase of 66%. Both HouseJoy and UrbanClap have been the fastest growing companies and the top players when it comes to offering home services.
The core idea of these platforms is to offer consumers high-quality services and at the same time create employment opportunities. While these companies facilitate all kinds of services, beauty is a big business. And these companies have portrayed these beauticians as the face of their service delivery. Most of the customers avail localized services in their neighbourhood, which do not follow high standards of hygiene or quality of products. Moreover, the equipment is also local. There is a demand for high-quality services in the market, at affordable prices. These companies have used technology to structure the highly unorganized services market in India.
When beauticians approach them, they are first invited to understand the basic skills required for the jobs listed on the app. Once they come on board, these beauticians have to undergo a 10-day rigorous training process and are also equipped to use the app efficiently, before they can start taking up assignments on their own.It is a partnership model, where beauticians can easily register with these companies through their app and start tracking customer requests in their neighbourhood. However, they have to notify about the non-availability of their service two days in advance or else pay penalty. The companies only register women with two–three years of experience in the beauty service, and different beauticians enrolled on these platforms sensed a high level of satisfaction and empowerment. They could now send their children to good schools and provide a better lifestyle to the family.
Besides training, advertising and promoting their services through the app, women also stay tuned to the latest products and technologies in the market. For every new service introduced, they undergo a refresher training course. Beauticians can purchase products as well as portable equipment needed for the services at a discounted price from these, which also ensures that the products are standardized across the chain.
The number of professionals joining these platforms has witnessed a three-fold increase in the last one year. This proves the efficiency of these platforms as employers or facilitators.
Future prospects:
Consumer lifestyles along with growing influence of global trends are now changing the face of wellness and making wellness a part of a consumer’s everyday life. While Indian players have forayed in the beauty and wellness industry, the potential still remains largely untapped. This is also attributable to the challenges that the players face, mainly due to the nascent stage of the industry.
The government on its part has to ensure that there are systemic checks for monitoring and that certified and licensed personnel are employed in critical service areas. Consumers and their needs will continue to evolve, driving the transition from remedial care to a more holistic view on preventive care. This augurs well for the wellness industry in India. Considering the challenges prevalent for the beauty wellness sector, each stakeholder needs to have a clear focus on issues corresponding to their area of operation.
Conclusion
Brands with purpose will have more compelling stories to tell. Consumers will vote for sustainable beauty and wellness with their time and wallets. The future is always bright – but only if we are well-equipped and surefooted as we move forward. Easy and efficient access to capital, start up support, and well governed public-private partnerships for beauty and wellness will create the necessary impact. Franchising is a great tool to attract more entrepreneurs into this industry and create jobs.
The year 2020 has placed enough evidence on the table during thisregard. The novel Coronavirus has shaken the whole globe by its roots. This is an example of one of the challenges this Future Of Pharma Industry faces: to constantly update infrastructure and R&D to combat new diseases and develop a cure for existing chronic diseases
The pharmaceutical industry is currently valued at $41 bn.Generic drugs, with 71% market share, from the largest segment of the Pharmaceutical industry in India. This is set to grow as 12% to 14% in finishing year of 2021-2022. In the domestic market by revenue, Anti-Infective (13.6%), Cardiac (12.4%) and Gastrointestinal (11.5%) had the biggest market share.
Curbing Costs:
Everything gets expensive with time. Rising costs and inflation also result in rising medical costs. Making health accessible and affordable for all may be a great task. The government has already initiated efforts therein direction with the Ayushmann Bharat initiative. However, considering that inflation may be an adynamic metric, curbing medical costs will remain an ongoing challenge.
Medical infrastructure:
This includes hospitals, medical colleges and education, medicines, pharmacies, small medical centres, labs, vaccines, machines that are utilized in procedures, the manufacturing infrastructure for medicines and everything that keeps the industry in place. Maintaining the standard of infrastructure and expanding it to all or anyway urban and rural areas is additionally challenge to the corporate.
Foreign regulations:
Many companies receive tons of their revenues from medical exports. The regulations and compliance norms of foreign countries may be a challenge that Indian pharma companies need to face. Trade restrictions, exports and import regulations, customs and taxes and lots of other caveats come when international trade comes into the image.
Investments and Recent Developments :
The Union Cabinet has given its nod for the amendment of existing Foreign Direct Investment (FDI) policy in the pharmaceutical sector in order to allow FDI up to 100% under the automatic route for manufacturing of medical devices subject to certain conditions.
The drugs and pharmaceuticals sector attracted cumulative FDI inflow worth US$ 16.86 billion between April 2000 and September 2020 consistent with the informationreleased by the Department for Promotion of Industry and Internal Trade (DPIIT). Some of the recent developments/investments within theIndian
The pharmaceutical sector is as follows:
In December 2020, Piramal Pharma Solutions announced plans to invest Rs. 235 crore (US$ 32 million) to expand its facility in Michigan, US, with additional capacity and new capabilities for development and manufacturing of active pharmaceutical ingredients (APIs). In November 2020, Indian Immunologicals (IIL) commenced work on Rs. 75 crore (US$ 10.17 million) viral antigen manufacturing facility in Genome Valley, Telangana, that will enhance its vaccine production capacity by 35% by October 2021. In October 2020, six generic drug makers–Dr. Reddy’s Laboratories, ZydusCadila, Glenmark Pharmaceuticals, Torrent Pharmaceuticals, Hetero Drugs and Ackerman Pharma signed an effect Hidalgo, a state in Mexico, to determine an outsized pharmaceutical cluster for production and logistics in Mexico. In May 2020, Jubilant Generics Ltd entered into a non-exclusive licencing agreement with US-based Gilead Sciences Inc to manufacture and sell the potential COVID-19 drug Remdesivir in 127 countries, including India. Affordable medicines under Pradhan MantriBhartiyaJanaushadhiPariyojana (PMBJP) achieved a record sales turnover of Rs 52 crore (US$ 7.38 million) in the month of April 2020.
Indian Diagnostic market analysis of 2021:
Growing Prevalence of Diseases and Launch of Technologically Advanced Procedures to Drive Growth” provides a comprehensive analysis of the diagnostic laboratories market. The report includes the cumulative revenue generated by the market players from diagnostic services, including both government and personaldiagnostic laboratories. The private diagnostic laboratories have been further explained with details on market share contributed by pathology tests and radiology tests, by Tier I, Tier II and Tier III Cities, and by hospital-based diagnostic laboratories, polyclinics, and independent diagnostic laboratories operating in India. The share by organized and unorganized players has also been provided intimately to obviouslyexplain thiscompetitive scenario within the market. The stakeholders of this report include diagnostic laboratories market players, laboratories equipment providers, companies involved in research and development activities, and therefore the new entrants and venture capitalists who wish to invest in the diagnostic laboratories market in future. Detailed snapshot on pathology tests market and radiology tests market is included within the report back to elucidate facts about the market intimately. The future analysis of the overall Indian diagnostic laboratories market has also been discussed along with recommendations from the analyst view.
The future Map:
Medicine spending in India is projected to grow 9-12% over subsequent five years, leading India to become one among the highest 10 countries in terms of drugs spending. Going forward, better growth in domestic sales would also depend on the facility of companies to align their product portfolio towards chronic therapies for diseases like cardiovascular, anti-diabetes, anti-depressants and anti-cancers, which are on the increase.
India needs clear and proactive interventions to form sure an all-conducive supply chain. This may not only boost local manufacturing, but also find ways to reduce dependence on external factors.. In consonance thereupon policy, it is vital for the government to work towards revamping the structure of the pharmaceutical industry. The govt launched targeted financial incentives to market manufacturing of raw materials, and to bring back a bigger production of APIs to India. The Union Cabinet took a decisive step to work out three API parks with common utilities, identifying and reducing the dependencies on China for 53 APIs, introduced the assembly Linked Incentive (PLI) scheme to further reiterate India’s aim to be self-reliant.
Around 35%-40% of the capacity is idle. The government must efficiently use the prevailing API units. Consistent with a McKinsey report, the driving factors for growing the domestic market in India are often attributed to the upper burden of diseases. The local production of APIs is incentivized through the rapidly growing population of the country. This provides avenues for pharmaceutical companies to not only cater domestically, but also enter international markets with comparatively higher age groups.
Shortage of delivery points and therefore the lack of accessibility to drugs continue to be bottlenecks even for the pharmaceutical companies to completely utilize the domestic market. The affordability of drugs will rise because of sustained growth in incomes and increase in coverage. Greater spending on healthcare and government sponsored programmes are necessary to hide the agricultural markets. Improving process is imperative for investments in healthcare infrastructure and financing, and better per capita income.
For a sustainable market and a robust rate of growth, innovative business models should be developed for equilibrium in drug price controlling and native manufacturing costs. Though the govt. has eased its protectionist policies, timely and effective implementation is crucial to affect the challenges of the pharmaceutical sector.
As countries are willing to require an edge within the Indian marketplace for the supply of COVID-19 vaccine and medical equipment, this is often the prospect for India to become truly atmanirbhar within the pharmaceutical segment.The Indian Government has taken many steps to set back costs and convey down healthcare expenses. Speedy introduction of generic drugs into the market has remained focusedand is predicted to profitthe Indian pharmaceutical companies. In addition, the thrust on rural health programmes, lifesaving drugs and preventive vaccines also augurs well for the pharmaceutical companies. Hence for now it can only be said that the situation is yet to be discovered to come any specific conclusion.
Conclusion
Moving from a time of transition to a bright future will depend upon how the Indian pharmaceutical industry can tap into the short- and longer-term opportunities identified above. What is clear is that the time is true for all stakeholders, from government, academia, and industry to take a position during this future, to realize the Indian government’s target of becoming a $5 trillion economy by 2025. However, to do so, the pharmaceutical industry will have to take some well-thought-out risks, embrace the proper opportunities and, importantly, fire on all cylinders! One solution to scale back risks is to optimize the potential of digital technologies to assist Indian pharmaceutical companies improve the efficiency and effectiveness of their drug development process, from discovery, through clinical trials to regulatory approval, making the entire process faster and cheaper than what’s currently possible.
In India, the revenue within the Fitness segment is projected to succeed at US$2,152m in 2021. Revenue is predicted to point out an annual rate of growth (CAGR 2021-2024) of 2.68%, leading to a projected market volume of US$2,331m by 2024.
Although the threat of corona virus has left the fitness industry ailing and barely able to stand with smaller gyms on the verge of shutting down, larger chains contemplating huge losses and unemployment becoming a very real prospect for thousands of trainers and support staff.There were approximately 5,500 gyms in Delhi employing around 1 lakh persons whose livelihood was compromised. Fitness trainers, executives, cleaners, equipment vendors and housekeeping staff were affected they were even struggling to cater to their daily needs.The owners had the burden to pay electricity bills, rent, bank EMIs, and school fees of their children and this could not be done when the business was closed. They were ready to follow the guidelines of the government to get back to the track.Since gyms across the country shut shop and the industry already crumbling under the pressure of the COVID-19 outbreak led to a lockdown in many parts of the country had hit fitness centres big and small — whether neighbourhood gyms, with maybe a couple of treadmills and a cross trainer or two, or nationwide chains like Gold’s Gym and Cult.fit that have at least 20 centres in one city alone.
Mumbai’s Cult.fit centres, asked many of their employees to resign over the phone no matter the employees suffering from financial constraints they were only offered with a compensation salary for 45 days which couldn’t oblige to the request. Over 800 employees were laid off. It was sad to see people getting removing in seconds. Apart from metro cities like Delhi and Mumbai, the fitness chain has a presence in cities like Indore, Amritsar, Kochi, Kota, Chandigarh, Jaipur, Surat, among others. And 90%trainers of the Cult. Fit gym continued to be there and was soon moved to a fixed plus variable model to tide over the crisis. All employees’ part of the downsizing was provided with a significant severance package to help them with the situation, including extended health insurance for them and their families.
As Nikhil Kakkar, COO of Gold’s Gym India, puts it, overseeing 150 gyms and employing 2,000 trainers. In Mumbai, all gyms closed on March 13, 2020. Rent forms a major chunk of the revenue, nearly 25 percent, and in seeks of waivers but landlords did not give any assurance. Payroll comprises 30 percent of the cost, while electricity took up 10 percent. Payments were also to be made for housekeeping, vaults, security and maintenance of equipment’s.
One of the most popular chains for gyms in the world – Gold’s Gym – had also filed for bankruptcy as the corona virus pandemic hit the US economy. The 55-year-old company was looking to pursue restructuring for its 700 centres across the world. However, its India business remained safe as assured by Karan Valecha, director and co-founder Gold’s Gym India. He claimed that the situation absolutely did not have any impact on Gold’s Gym India as a Master Franchise and yet their commitment for providing customers with the best fitness experience was full of confidence.
Whereas on the other hand Pravesh Gaur, who owns the Fast Fit chain of gyms in Delhi and Faridabad, had sent some of his staff on unpaid leave and were looking at a loss of more than 30 percent of annual sales and was left with no other option than shut. Each of his gyms employs nearly 20 people, including trainers, cleaning staff and receptionists. The trainers were at least kept on board while rest members were kept off the board.
But according to Chirag Sethi, owner of Anytime Fitness outlets in Delhi’s Malviya Nagar and Saket, the current state of the fitness industry in India was a far cry from what it was in April last year. He reveals that many mothers who seek gym memberships owing to extra time on their hands due to the onset of the pandemic it has got to a point that people are scared to even enter the gyms for which bearing 100 percent losses, while it would normally have made a profit of Rs 20-28 lakh every month, but ever since the lockdown began it was registered a loss of Rs 60-80 lakh,”
There are around 24,000 gyms and studios in the country, according to an estimate by Fitternity, a web aggregator for fitness outlets. To prevent their businesses from running completely dry, many have taken to providing online training sessions over WhatsApp, Skype, and FaceTime. Cult.fit is now imparting online training sessions for its members on its app, with trainers doing their best to instruct in as much detail as possible.
Sethi, who is also the Vice-President of the Delhi Gym Association that represents over 3000 gyms in the Capital, is also participating in the online campaign, urging clients to pre-buy their memberships to help sustain the fitness centres, especially the smaller gyms, and stop them from shutting. The smaller gyms had gone bankrupt as they had to access to aid (capital). It had become a fight for survival with a hand to mouth situation.
Even as the gyms open in the post-COVID world, the fitness industry the world over is set to witness a major change — with social distancing and hygiene measures becoming the prime focus. Even across the globe, where things have already started opening up, gyms are bracing for the new normal. For instance, the operators of Britain’s 4,000 gyms are in advanced plans for reopening once they are given the all-clear. When gyms do finally open, capacity is likely to be reduced by half to maintain the two-metre distancing, while personal trainers will have to offer advice from a distance. Members will be able to use an app to monitor when their gym is quieter and plan their visits accordingly. An app was also developed, wherein members were assigned time slots for a limited number of days. As opposed to having 50-60 people drop in during peak hours (morning and evening), a maximum of 15 will be allowed with two or three trainers deployed to help them and out of the six treadmills on the floor, only two were operational to ensure social distancing. Sanitisation exercises with disinfectants being sprayed on exercise equipment’s after every hour and temperature checks will be the new norm, as was witnessed in several gym outlets before the lockdown began.
Hence comparing the branded gyms like Gold’s Gym and Cult.Fit along with their franchises with other small and non- branded gyms and fitness centres the outcome is the difference of the capital that made the branded fitness companies survive during this hardship but yet on the other side the non branded and small fitness centres with less capital couldn’t survive, because Capital is always scarce in growing a business. And in franchising the capital needed to expand is provided by the franchisee.
The year 2020 bought a few lots of changes within the way we eat, think, act, live, but most of all, it caused a change within the way we treat our minds and bodies not only this but also being lively and spending quality time with the loved ones made a grave impact
While sales for home workout equipment sky-rocketed over e-commerce sites, fitness influencers took charge and began multiple series to assist people workout at the comfort of their homes.
The fitness industry is evolving rapidly with the arrival of a budding ecosystem comprising consumers, service and equipment providers, complementary industries, and government initiatives. Indians became more health-conscious and have started taking note of their daily habits and lifestyle. However, the thought of a healthy mind during a healthy body isn’t new Indians – yoga, akhadas, Ayurveda, and meditation have always been a neighbourhood of our culture modern lifestyle again gave us a reason to get in touch with our roots.
The delivery of fitness to the buyer is evolving
In an attempt to curtail spread of the virus, many government entities forced the closure of fitness facilities everywhere the planet. These mandated shutdowns have resulted in the bankruptcy of huge health spa operators like 24-Hour Fitness and city Sports International, also because the closure of studio operators likes Flywheel and various independent business owners. These closures are a big source of disruption and have resulted in lost jobs and incomes for thousands of health and exercise professionals. However, these closures have also encouraged more widespread use of virtual programs. While home-based workouts aren’t new, the pandemic has spawned an explosion of online services that represent a completely new way of delivering workout programs to consumers.
Pratik Kalra, a personal trainer at Fitness First’s Noida branch had claimed to put the annual membership fee on hold, which were resumed after the gym could resume operations. In the meantime, they were also offering online personal training sessions to interested customers at a nominal rate. To retain its patrons’ interest, Fitness First is also offering online live fitness videos with celebrities like Jonty Rhodes, Mouni Roy and Mandira Bedi, for Rs 2,000 for five sessions.
Online classes are also being dished out to regular customers of gyms with 900 members each, over Facebook, Instagram and Zoom, free of cost “just to keep the members with them”. Mumbai’s JG’S Fitness Centre, which has got no new member registrations since the outbreak, has initiated online fitness consultations and training sessions to keep the banks rolling.
But online classes of gyms are what food delivery is for fine-diners — a patch on their actual sales. Meanwhile, some of them have come together for an online campaign to highlight what needs to be done to save the “fitness industry”. Kakkar is part of bodyandstrength.com, wherein they post requests by top fitness professionals and centre heads — including asking for a moratorium on utility bills, GST waiver for the coming months and a freeze on rental for the affected months.
Facilities like studios and health clubs need to pay rent for a physical location; when the mandated shutdowns occurred, operators had to shut their businesses and forgo the power to gather revenue while still being contractually obligated to pay rent. Companies that provide live-stream fitness classes, like Peloton, Les Mills and Mirror, on demand have a serious competitive advantage over traditional fitness facilities therein they will deliver workouts to an almost unlimited number of consumers while paying only a fraction in rent. Video fitness providers were experiencing gradual growth before the spring of 2020, but as governments established the shelter-in-place orders that forced facilities to shut, that growth became exponential.
Virtual fitness classes are often delivered one among two ways: asynchronously (i.e., on demand), meaning a consumer can choose a workout from a library of previously recorded programs; or synchronously (i.e., live streams), where the buyer follows alongside class because it is being taught live and broadcast over the web. Whether on-demand or live, consumers trying to find workout solutions reception quickly adapted and have become familiar with the convenience of doing an instructor-led workout from the comfort of their house. This alteration in consumer behaviour will create business opportunities who can begin offering streaming workouts of their own.
Large companies aren’t the sole ones providing streaming workouts. When health and exercise professionals were placed on furlough or terminated by their employers, many responded by using services like FaceTime, Zoom or Facebook Live to continue working with clients and teaching group fitness classes. Aimee Nicotera, an ACE Certified Group Fitness Instructor based in Massachusetts, was placed on furlough and ultimately terminated by a national health spa company. The allowance of Social media on health and exercise professionals to plug on to the buyer
Another disruptive force that’s changing the way that health and exercise professionals connect with clients is that the use of social media. The normal model of a fitness business involves working with clients during a physical location, like a health spa or travelling to figure with clients directly in their homes. Before COVID-19, that model was already beginning to change and now even more health and exercise professionals are adapting to the utilization of social media to draw in new clients. Personal trainers can design and produce workout programs for a spread of outcomes, from weight loss to muscle growth. Between streaming platforms and social media channels, health, and exercise professionals have a spread of the way to interact with and deliver solutions to clients. However, many individuals marketing fitness services via social media are relying totally on physical appearance or creative content to market their services.
During this ongoing pandemic, when we are all bound to live a restricted life under the constant fear of infection risks, people have been more prone toanxiety. The continuous flow of negative news, the inadequacy of daily resources, everything is adding to this growing anxiety and depression. Being confined at home for such long periods of time can be mentally challenging for us. When our mind is flooded with the uncertainty of the future, we often experience sleepless nights causing fatigue. Many of us are unable to relax our mind during this time thereby increasing the stress on our minds.
Conclusion
In the post-pandemic world, services that relied heavily or entirely on customer mobility have been the worst-hit. Transportation services like Uber, fitness centres, and the tourism industry, for instance, have taken heavy losses and – in many cases – have permanently closed operations. Other businesses have been compelled to reduce their workforce, give up their physical office addresses and restrict client interactions to digital conversations.
As a business evaluates its plans for delivering services optimally in a post-pandemic world, it needs to find the answers to questions about whether the markets and geographies it has been serving remain profitable, which core technology and business practices need to be modified and how the team can be best enabled to keep delivering in the new normal.
The COVID-19 lockdown was a situation no one could have predicted. Now, more than ever, it is time for businesses to be at their most agile and to adapt intelligently and optimally to a mostly-online way of working. This requires the active support of the team and an extensive understanding of how markets are likely to work now and in the foreseeable future.
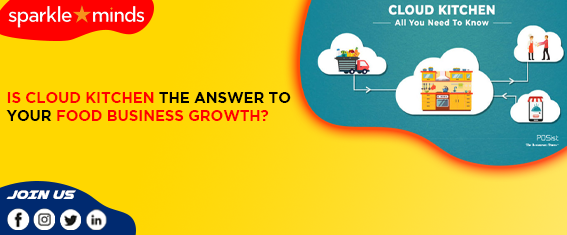
A new concept introduced in the food industry as Cloud kitchen also referred to as ghost kitchen, virtual kitchen commissary kitchen or dark kitchen they have different names but they refer to a new model where it is a delivery-only restaurant that has no physical space for dine-in. As the global cloud kitchen market size was valued at $0.83 billion in 2019 and is anticipated to reach $2.23 billion by 2027 with a CAGR of 13.4% from 2021 to 2027. The market is expected to see the highest demand share coming from China and India, which currently hold more than 50% market share. The main focus of the Cloud Kitchen is in food preparation and delivery rather than anything else. There is no perturbation about table management, location, decor, etc, which further saves your business running cost with lesser space and staff. One of the biggest advantages and fact is the ability to target multiple segments of markets simultaneously. You could be running multiple brands out of the same kitchen, and serving various demographics at the same time, while benefiting from economies of scale you can also run into brands out of the same kitchen. It is also very flexible and assessing to the leads to lower costs, better efficiency, and reduced risks. The lack of a physical storefront makes it toilsome to build a natural customer. There is also a major dependency on aggregators to facilities delivery making it crucial to develop an independent digital presence. The curator’s desire to deliver the experience in a box is also a challenge as it depends not only on the packaging but also on the caution with which the food is delivered.
Metrics aside, much of the hype around cloud kitchens is being driven by changing preferences. For long, delivery was synonymous with pizza, or Chinese.
Now, with cloud kitchen companies rapidly expanding their portfolios, customers have a bigger plate to choose from.
Revenues of Cloud Kitchen Vs Traditional Restaurant Models
If you are a restaurateur looking to make comparable revenue from a cloud kitchen model, there needs to be the recognition that revenue per store at a cloud kitchen is typically much lower than the revenue generated by one 50 seated dine-in restaurant. It may take about 4 or 5 successful cloud kitchens to attain a similar top-line as that of one dine-in restaurant. Or you need to be able to have a very strong digital marketing program and spend intelligently to keep the audience engaged in your catchment area, when this is done, the top line can surely soar to different levels Even if you run a multi-brand format from one cloud kitchen, the revenue generated from those individual brands will not be comparable to the revenue of one dine-in restaurant if the digital activity is not done correctly. The stagnation in revenue has meant that even high-street restaurants, once dismissive of cloud kitchens, are willing to change tack. A successful restaurateur understands the importance of both and uses them both for driving revenue.
Cloud Kitchen- Pre COVID and Post COVID.
An obligation to reduce non-essential outdoor activities, and an increased supply of cloud kitchens in both existing brands and new entrants will accelerate the pre- Covid trend of ordering in and takeaways, and become a permanent shift post-crisis,
With the coronavirus lockdown keeping restaurants closed and would-be diners at home, takeaway meal options have been booming in India. And there are signs that the shift toward home-delivered food is here to stay. Cloud kitchen has better suited to the needs of socially distanced customers than traditional dine-in restaurants. They’re also able to minimize some costs, such as rent, and without wait staff require fewer people on the payroll.
Earlier, the contribution by cloud kitchens was estimated to be 20 percent of the food delivery market. However, this percentage is changing and will undergo drastic changes in the favour of cloud kitchens.
As the food industry has undergone a tectonic shift which is likely to continue in the near future, the option of ordering food through apps has boosted cloud kitchens.
When the food delivery company,Swiggy started cloud kitchens three years ago, it had been a sideshow in its food delivery business. The concept caught on as restaurant brands that had a following in one area could expand easily into new localities or maybe other cities. Investment in land was reduced because these kitchens might be smaller and didn’t need premium locations, aside from doing away with seating and therefore the staff for serving. And now Swiggy has co-created nearly 200 brands since the launch of this model using existing kitchens of restaurants in February
Various models arose. Some introduced cloud kitchens additionally to restaurants for expansion, like Chennai’s Buhari becoming available in Coimbatore. Others like Rebel Foods created fully virtual brands that only came from dark kitchens. This became a replacement land and services play as restaurants only had to supply cooking staff while everything else, including cleaning and maintenance, might be outsourced.
The current plot of Cloud Kitchen
It’s a grim reality that many restaurants will go out of business. Every restaurant is currently in survival mode. In the short term, it will become critical for traditional restaurants to pivot to delivery for survival. Even if they do make the pivot, many still will not make it. In the current environment and with the continued uncertainty of the COVID-19 pandemic, cloud kitchens or food and beverages outlets backed by a cloud kitchen network have a better chance of survival and are likely the future of the food industry.
For the business seeker who is exploring to buy a food franchise in India, you may want to look at brands who are offering a successful cloud kitchen franchising model for sale which hasa strong tech backing and a very robust supply chain in place.
The restaurant is an old age vintage car, used for showcasing and branding. On the other hand, cloud kitchen is its fast-paced futuristic- high-tech cousin.
2020 was year of consternation and confusion as consumers around the world struggled to find what they needed under circumstances that changed weekly. Counterintuitively for many companies, it was the best year in their history as consumers had a range of new needs resulting from working from home and various levels of lockdowns. However, for other conventional businesses, more specifically retailers in malls, urban areas in countries with strict lockdown orders, it was a year of major losses. They surely have been jolted and have created their own pathways to becoming relevant in a post covid world.
We are extremely confident that some very big franchise brands will emanate from this pandemic in India and across the world as we prepare for opportunities that lay ahead. These brands will use all the means and tools available for the next-gen consumer and use interesting modern franchising models and the resources that are now at our disposals, which hitherto, were non-existent.
Franchising is growing at an impressive pace in India. Franchising has witnessed a growth of around 30-35% over the last four-five years and the overall turnover is estimated at around INR 938 billion. Currently, the sector contributes nearly 1.8% to the Indian GDP and is estimated to contribute to around 4% by 2022
India has over 4600 franchisors which comprise of:
• 16% – Global brands • 34% – National brands • 50% – Regional brands
This country has nearly 2,00,000 franchise outlets being operated by and under 1,70,000 franchisees and nearly 60% of franchise locations are in a unit franchise format. These are pre-pandemic numbers, while the segment is poised for the explosion, by the beginning of 2022. The franchise formats for brands have been popular to experiment with because of the brand reputation they’ve earned and who wants to use that reputation to attract and attach many customers to them.
The significant benefits of starting a franchise business in India right now are: • Lower operating cost • Local Business Knowledge • Rapid Expansion • Branding • Training and technical know-how • Less risk for franchisee • Easy access to capital
Lower rate of failure :
Franchises have a lower rate of failure as compared to start-ups. According to a study by IBM and Oxford in 2016, 90% of the Indian start-ups fail within the first five years, against only 15% of franchises. Since the business concept has already been worked out with the existing loopholes been fixed, the model today is efficient, low risk, and low cost over any start-up. Thus, making it more appealing to the investor.
Increasing income and purchasing power :
Indian disposable income was approximately INR 131 trillion in 2018 and is expected to double by 2025. The rising income levels in rural and urban India have resulted in increased spending on discretionary items as against necessities. This rise in income and spending capacity across India coupled with increased awareness, has created a substantial demand for domestic and international brands. A large number of companies are expanding beyond tier-I cities and increasing their presence by adopting the franchise model. Hence a large number of franchisee seekers have emerged in TIER II and TIER III cities and towns of India seeking to buy popular franchise brands which they see which are popular in bigger cities around them.
Privatization in different sectors :
With the rapid privatization in India across various sectors such as education, healthcare, telecommunication, and others, there is a constant rise in the influx of international brands in the country. With this increase, the scope for franchising has also gone up. Today, companies across sectors such as EuroKids, Ferns and Petals, Vakrangee, Connect India, and DTDC are key examples of successful privatization and franchising in India.
First-time entrepreneurs:
The newfound entrepreneurial spirit of young Indians has led many individuals to enter the franchise business. Presently, around 35% of all franchise owners have been first-timers in business. These entrepreneurs choose franchising due to the range of benefits it offers such as reduced risk, association with an established brand, training, and support, etc.
• Relatively higher unemployment rates, with both lower-cost workers and seasoned career professionals seeking opportunities. • Favorable market conditions that provide ready access to capital for investing in franchises. • Available commercial real estate due to business closures in 2020. • Several existing franchises available for sale due to owners being affected by COVID-19 or not being able to manage the working capital requirements. • Several franchisors are offering preferential one-time terms while signing their franchise agreements in India. Prospective franchisees can surely negotiate on some terms based on the current scenario for their advantage.
Potential of Franchising in India, Industry-wise in Post Covid Era.
Whether you are buying a franchise in India post covid or franchising your business across India post-2021, here is a snapshot of 6 different segments we have covered for your understanding. You could stay connected with the sparkleminds blog for the latest on the franchising industry of India as we pretty much cover all types of businesses and you can get the information you seek about any specific business, brand, segment or location.
Healthcare:
Driven by better healthcare awareness, rise in incomes increased access to insurance and lifestyle-related diseases, India’s healthcare market is expected to reach USD372 billion by 2022.4 The Indian government aims at increasing the healthcare spending to 2.5 per cent of the GDP (gross domestic product) by 2025. Franchising will be the vehicle to push products and services, many medical store brands will be up, and many are looking to invest in polyclinics, fertility centres, animal clinics and so on so forth.
Mental Health Services, is a new area that will open with many mental health care centres, like Psychiatric, Psychological, and mental wellness service centres that will open with people using many AI tools in helping clients.
The Indian ‘eHealth’ sector is at a tipping point and is projected to grow by ~13x, to become a $16 Bn opportunity by FY 25. The $135 Billion Indian healthcare industry is at an exciting tipping point, with the Indian Government prioritizing healthcare as one of the key focus areas for the next few years. The Government plans to increase its healthcare spending from the current 1.6% to 2.5% of the GDP until FY 25.
There is significant opportunity for improving the healthcare services across the country, especially in Bharat, where penetration of quality and affordable outpatient & inpatient care services is limited. The eHealth sector will have 3 potential growth scenarios in terms of the number of tapped households over the next 5 years:
Base Scenario: eHealth will tap 41 Mn households by FY 25, growing at eHealth’s historic 2 Yr. CAGR of 57%.
Moderate Scenario: eHealth will tap 57 Mn households by FY 25, growing at grocery’s historic 2 Yr. CAGR of 68%.
Aggressive Scenario: eHealth will tap 68 Mn households by FY 25, growing at Foodtech’s historic 3 Yr. CAGR of 74%.
India is home to around 5,295 health tech startups, out of which 133 are funded eHealth startups. The eHealth market in the country is expected to reach $10.6 Bn by 2025. However, it will only be 1.6% of the total addressable healthcare market, pegged to reach $638 Bn by 2025. This amply indicates the huge headroom for growth and the massive opportunity that can be leveraged by the eHealth sector.
Healthcare companies or brand can make the most of the growth this segment is seeing by franchising and appointing franchises who are scrambling for a piece of the healthcare pie which otherwise is not possible for individual entrepreneurs for the sheer scale of investments that could be required. Hence entrepreneurs could join the segment for as low as Rs2 Lakhs by starting a collection centre or as high as a crore for a diagnostic lab. For the brand, they get entrepreneurs at the last mile, ensuring a asset-light expansion model.
E-Education: Print in India shrunk to 25-30% of pre-Covid levels. Also, since the lockdown led to the adoption of digital as the mainstream mode of teaching and learning, the demand for educational books dropped by 40-50% due to the closing of schools and colleges.
The COVID-19 has resulted in schools shut all across the world. Globally, over 1.2 billion children are out of the classroom. As a result, education has changed dramatically, with the distinctive rise of e-learning, whereby teaching is undertaken remotely and on digital platforms. Research suggests that online learning has been shown to increase retention of information, and take less time, meaning the changes coronavirus have caused might be here to stay. It is clear that this pandemic has utterly disrupted an education system that many asserts was already losing its relevance.
21 Lessons for the 21st Century, a book published by scholar Yuval Noah Harari outlines how schools continue to focus on traditional academic skills and rote learning, rather than on skills such as critical thinking and adaptability, which will be more important for success in the future. Could the move to online learning be the catalyst to create a new, more effective method of educating students?
While some worry that the hasty nature of the transition online may have hindered this goal, others plan to make e-learning part of their ‘new normal’ after experiencing the benefits first-hand.
The importance of disseminating knowledge is highlighted through COVID-19. Major world events are often an inflexion point for rapid innovation – a clear example is the rise of e-commerce post-SARS. While we have yet to see whether this will apply to e-learning post-COVID-19, it is one of the few sectors where investment has not dried up. What has been made clear through this pandemic is the importance of disseminating knowledge across borders, companies, and all parts of society.
If online learning technology can play a role here, it is incumbent upon all of us to explore its full potential. Edutech platform upGrad reached a million users recently. It grew 100% in 9 months from the start of the financial year and is targeting Rs 2,500 crore in revenue for FY21-22. The platform has forecasted that it will reach the 2 million user mark within the next 18 months.
Between April and December 2020, ‘edtech’ searches gained 60 percent on the Indian internet, according to Google Trends. Searches for individual companies such as BYJU’S, Vedantu, Toppr, and others that cater to India’s 265 million school-going students — the highest in the world — gained even further. A joint report by BARC India and Nielsen revealed that there was a 30 percent increase in the time spent on education apps in the first three months of lockdown.
The Future: Physical vs Online: Covid-19 has altered the landscape of education. Even large universities are adopting e-learning and thus in turn saving on investment in more physical infrastructure. This is also making education more accessible and affordable. Ever since the pandemic, upGrad enabled over 100 universities and colleges, including MHRD’s NIRF Top 100 universities to replicate their classes online. We have seen an upsurge of online education brands seeking franchises at FranchiseBazar.com. Almost every segment which had a physical classroom presence is now looking at additional physical classroom franchises who offer virtual classes to students in the catchment area and provide in person attention as well. This is the norm most education franchisors in India are adopting. National Skill Development Corporation or NSDC is pushing hard for private participation in this segment as well, as companies tied up with this government initiative also need last-mile classrooms and are using the franchise model for expansion.
Retail Convenience Stores: According to a survey about the impact of the coronavirus (COVID-19) on Indians in May 2020, retail stores seemed more reliable in terms of sourcing essential grocery. For those ordering online, only ten percent got everything they needed easily, compared to 40 percent among retail store shoppers. India implemented a lockdown for 21 days, announced on March 24, 2020. This was after the “Janata Curfew” on March 22, 2020 – a so-called practise lockdown. Panic-buying commenced among consumers days before the lockdown was announced, much like in other countries. This lockdown was the largest in the world, restricting 1.3 billion people, extended until May 3, 2020. Reliance Retail will exit direct sale of packaged food, grocery and FMCG goods on its e-commerce platform JioMart by roping in Kirana stores as franchise partners that will sell these products to consumers in their respective neighbourhoods. This marks a shift in strategy that differentiates it from other big online grocery platforms such as Big Basket, Amazon and Grofers. This also opens up the gates for millions of shop keepers or Kirana store owners to convert their existing shop into a reliance jiomart franchise and join the organized retail revolution underway in India.
100’s of other supermarket brands or franchisors are also now in expansion mode in India as they have seen unprecedented demand during this phase and need a local convenience store close to the customer to fulfil their immediate requirements. This is the beginning of the consolidation of the kirana industry of India, delivering to the doorsteps of crores of customers now backed by strong online players like Reliance, Walmart, Amazon & Alibaba in India.
E-commerce:
The Indian e-retail market is primed to reach nearly 300 to 350 million shoppers over the next five years—propelling the online Gross Merchandise Value (GMV) to $100 to 120 billion by 2025. As Indian e-retail sees a steep increase in shopper penetration, driven by lower data prices and investments to improve customer experience, online platforms are innovating to onboard the next hundreds of millions of shoppers.
49% of Indian consumers say online sites and apps became the preferred mode of shopping for them in the last 12 months, as per a Local Circles survey. Safety from Covid-19 and convenience were cited as top reasons by consumers for using eCommerce. 69% of those who shop on eCommerce bought groceries/essential supplies online. Consumers used large e-commerce platforms as well as small verticals or local e-commerce sites to purchase groceries and essentials.
This spike in B2C ecommerce in India is of course due to existing online shoppers stocking up on essentials given the coronavirus outbreak and the lockdown imposed by the Government (to check its spread). However, it also consists of perhaps two more segments –apart from the one that buys online, regularly. India’s e-commerce is expected to reach 99 billion dollars by 2024, growing at a 27 per cent CAGR over 2019-24 with grocery and fashion/apparel likely to be the key drivers of incremental growth.
India’s e-commerce market is projected to grow by 84 per cent between now and 2024 to about $111 billion (from about $60 billion in 2020) driven by mobile shopping, which is projected to grow 21 per cent annually over the next four years, the report said.
Brands like Lenskart.com have witnessed great push from their retail presence despite seeming like an online brand, garnering a major share from their offline sales through franchise and own stores. This trend will continue for several ecommerce & retail brands where touch and feel is an important criterion for converting consumers. A Lot of Indian retail and ecommerce brands are deploying this hybrid strategy for growth. All conventional players like Bata, Raymonds, Lakme, Prestige and several others are all in an aggressive franchise and ecommerce expansion mode in India.
Logistics :
The immediate impact of the pandemic on the logistic sector has been a sharp fall in freight availability due to restrictions on the production of non-essential goods, and shortage of fleet for movement of goods owing to the dearth of drivers and a consequent spike in truck rentals and air freight prices. More than 9 percent of the shipments were stuck, 21 percent of the orders were delayed and the delivery percentage has seen a clear decline of 19 percent, forcing the logistics sector to face the brunt of the crisis. More than 9 percent of the shipments were stuck, 21 percent of the orders were delayed and the delivery percentage has seen a clear decline of 19 percent, forcing the logistics sector to face the brunt of the crisis.
According to Economic Survey, the country’s logistics industry is expected to touch $215 billion by the end of 2020, growing at a CAGR of 10.5 percent. It provides employment to more than 22 million people. Rapid and technological advancements in digital technologies, changing consumer preferences due to e-commerce, government reforms, and shift in service sourcing strategies are expected to lead the transformation of the Indian logistics ecosystem. In the new normal, technology has proven its utility and adaptability.
Strong market trends towards the e-commerce segment continue to transform how brands and consumers interact. The pandemic has brought an increase in the demand for essential items such as groceries, food, and pharmaceuticals. Many logistics companies cater to this demand whilst adhering to safety protocols with OTP-based contactless delivery of items. Leveraging state-of-the-art technology, logistics aggregators should focus on increasing the efficiency of services and optimizing cost.
The Union Budget 2021 promises increased spending on infrastructure, focusing on new and improved economic corridors, and road and railway infrastructure. The Government’s push to port, road and rail infrastructure through various investments, initiatives and projects will further add to the development of the logistics industry in India. With faster construction of the Dedicated Freight Corridors and road highways, not only will the logistics sector benefit, but it will be able to add strong support to our domestic manufacturing programs.
How COVID-19 Shot Franchising into the Future
Weaker Businesses Are Going to Close: Several businesses are just not strong enough to survive due to weak margins and poor cash flow management. Businesses will survive the quarantine, but the wheels will have been set in motion to force their closure within a year or so. Businesses that will be so strapped for cash will be unable to market or maintain operations to a decent level, gradually eroding their business. Not only will consumers be more cautious about their expenses, the ones which remain will visit the businesses marketing more aggressively.
The Rise of the Multi-Unit Operator: Multi-unit operators have been growing for years and now own more than half of all franchise units. Economies of scale help make them sustainable businesses even with lower unit-level margins. Well-capitalized operators will scoop up the units that are having trouble staying afloat but still have the potential to turn a profit. This will accelerate. This is perhaps the most profound trend with regards to the future of franchise coaching.
For the franchising business model, the combination of strong businesses and the multi-unit operator will be a positive as larger systems will be better equipped to assist their operators in surviving than the regular “mom and pop shop” down the street. The overall diversity in the ecosystem will be reduced, but out of all the units that weather the storm, the overall proportion of franchised and corporate chains will be increased.
Changes in the Talent Pool and Discretionary Income:
Overall, with all these units shuttering, franchise businesses should see a return to equilibrium with regards to the current labour shortage. This will help them put better staff in place, should reduce employee turnover and thus improve margins due to less time spent retraining. However, over the next 12 to 24 months, higher unemployment means that there will be less discretionary income to spend and that may negatively affect certain franchise verticals. This impacts the strategies business owners will need to put in place to attract customers.
Increased Focus on Operational Efficiency:
Businesses will be put under greater pressure to maintain profitability. They will look at ways to run a tighter ship by simplifying their operations, investing in technology and cutting costs where possible. Overall, this is good news for suppliers in the franchise space who focus on operational efficiency. The next few months will be tough for everyone in franchising, but there is light at the end of the tunnel.
Multiple Concept Franchising:
Multiple concept franchises capitalize on an old trick: diversification. Why count on one brand when you can count on many? Franchisees are increasingly trading under several brand umbrellas beneath a single corporate roof. That reduces operational expenses and allows franchisees to work with the same team even when they take on a new brand. In an economic downturn, they can exploit their most profitable markets and hedge against the losses of their unprofitable franchises. There’s something in it for franchisors, too. It helps you to source franchisees with significant skill and experience.
Hence, this could be a great time to franchise your business in India or elsewhere across the globe and set the wheels in motion for your business growth, capitalizing on the real estate, manpower, logistics, technology and other resources which are possibly available at their best costs ever. Franchisors could start the preparation on multiple levels for the expected franchising boom: strategic planning, operations documentation, site selection, marketing and messaging, and franchisee profiling. We could help you create your franchise marketing kits, franchise financials in India specifically building the ROI, franchise fees, royalties from a market reality perspective, franchise manuals, franchise agreements and detailed franchise marketing. Exclusively Published by Sparkleminds Bureau. All rights reserved.
Every businessman was planning their new growth goals for the year 2020 and the whole game of business transformed by the impact of a new virus. The blow of Corona virus (COVID-19) is pervasive worldwide and all businesses are affected by it. Leaders are facing a wide range of issues like ensuring the safety of their employees and customers, prop up cash and liquidity, supporting complex government support programs and reorienting operations. As COVID-19 poses further economic threat and uncertainty, managing risk, maximizing profit and ensuring the stability of your business demands a deep analysis of dynamics of changing market conditions and government policy. Timely and deep analysis of economic and political scenario for the pandemic and the potential ways of recovery for individual economies is increasingly crucial to business planning and commercial decisions.
While there was always pressure on the development team to generate new franchisees and unit openings, that pressure could very well increase, now that franchisors have suffered a drop in revenues from loss of royalties to fewer or delayed new openings.
The risk here is that this pressure could lead to exacerbating the same mistakes that have plagued many franchisors for years: choosing the wrong franchisees, sites, and territories to achieve short-term objectives. Don’t let that happen. Take the time to assess your business and build a plan for long-term success.
RISE OF TECHNOLOGY
Talent and technology are blending in innovative ways to enhance customer experience, operational efficiency and competitive advantage. Digitalisation has become a necessity which we have to use to gain positive outcomes. Whether it’s channelling data, streamlining processes or shaping entirely new ways of business, thesis about unifying every part of the enterprise in a common purpose. The use of technology to increase efficiency is used by small and medium-sized companies as well.
AUTOMATION
COVID-19 has already urged companies to accept their future far quicker than they would have naturally – from agile working and digitalization, to automation and investment in renewables. If you know where you are going, actions to respond to the crisis today can set you up for the years ahead.
Understanding ‘what’s next’ for your business means knowing what’s next for the world; what may have been right for your business before-COVID may not be right in the ‘new reality’ that we will soon face. Anticipating a post COVID-19 world requires prediction of two key questions: when will it happen; and what will it look like?
It seems India is slowly moving towards a gradual removal of the lockdown for some sectors of the economy. The biggest challenge businesses will face will be restarting their operations. Even while a larger part of the empowering system continues to be in lockdown. Parts like public transportation, etc., is likely to continue to be in lockdown and within the constraints of what we are allowed to do, we’re going to have to ensure that we get our businesses back on track.
OPERATION OF OFFICES AND MANUFACTURING UNITS
There are two aspects to the lockdown, one is operations for offices and the other is operations for manufacturing units. The government will have a major part regarding these two issues. They are going to allow the relaxation of the lockdown in a phased manner. We are going to have to really go through a series of steps to ensure that we are complying with those government guidelines, but at the same time, ensuring that our people are safe, and are able to be active as well, because at the end of the day, we have to run a business.
Overcome Uncertainty: What to do now and next
As governments make significant interventions in response to the coronavirus, businesses are rapidly adjusting to the changing needs of their people, their customers and suppliers, while navigating the financial and operational challenges. With every industry, function and geography affected, the amount of potential change to think through can be disheartening. We are here to help.
Charting out the list of only the necessary employees
A detailed planning activity, where we need to identify which employees really need to come to work, even after the lockdown is lifted. Others can continue to work from home. That clarity is important.
Regular testing and Transportation of employees
Companies should ensure transportation for their workers. At the offices there should be a series of checkpoints where testing can be done. There should be holding areas for colleagues to ensure that a red flag can be raised if someone’s feeling unwell.
NO CROWDING!!
We have to ensure there is no crowding in our office spaces, ensure that only 25 or 50% of the workspace is actually occupied.
Sanitization and Doctors
The workplace should be sanitized regularly and should always have a doctor to assist with any medical inconvenience.
These have to be strategized efforts to ensure that while we open up our offices, we take every step conceivable to minimize the impact on employees and ensure their wellbeing and safety.
There will be other elements that are easier for a smaller company, but pose significant challenges for a large company. This can include transportation. larger organization will face a lot more difficulty to take control of the commute or put people in guest houses or other accommodation than smaller companies. This will put significant financial strain on a lot of organizations. So, there will be a drop in the pace of operations. The focus has to be on enabling work from home, wherever possible, so that it’s just a proportion of the employees that are impacted. Even when we open up, not everyone will be allowed into office at the same time. You have to create schedules where teams come in at certain times during the day complete their work, and leave.
We all know that the condition is grave but there is always a silver lining. The fact that more people are working from home is making it easier for some organizations to reach their clients, current and potential. People have learned to engage more effectively over video calls than they did earlier which opens an opportunity to utilize untapped markets – countries that until now have been either too far, too small or difficult to penetrate. We know that we will overcome this grave situation with our smart strategies. Hope you all stay safe and healthy.
At present, each country in this world is
battling COVID-19 brought about by the fatal coronavirus. The number of cases
has been expanding each day around the globe and have seriously influenced
India as well which has created a global scenario of panic and furor.
Alongside medical problems, COVID-19 has
influenced the economy of the world quite adversely as well.
If we trace closely, monetary downturns and
pandemics have historically been responsible for changing the direction of
governments, economies and organizations thereby, adjusting the course of
economic graphs in history. A recession normally results in a speeding up in
plan of action change, driving down expenses to serve and costs. Thus,
pandemics have and will in general empower altogether new classes of
organizations. It additionally turns out to be very evident that the pandemic
and the recession caused due to it, are accelerants to advancement as opposed
to being immediate reasons for it.
At a time like this, the smart option to
thrive in the market is to invest in franchise businesses. Franchise businesses
have more credibility than independent businesses because of their survival
rate. For any business to develop as a franchise brand, they must have survived
various economic fluctuations in the market. Therefore, post the pandemic, the
safest option is to invest in a franchise which has already had an experience
and has sustained. What this means for any franchisor or a brand is that there
will be some very qualitative franchises out there looking for different types
of opportunities and you may want to start putting the building blocks in place
to attract them during the recovery sessions. You would want to get the best of
these entrepreneurs engaged to your business.
To gain more information regarding how to go about franchising, it is preferable to refer to credible websites and sources like Sparkleminds which provide a range of extensive services as a guide to initiate and expand franchise business opportunities. Sparkleminds offers the following services which can prove helpful to both the entrepreneurs and the business houses,
A tool
guide to begin franchising
Franchise
Consultancy
Market
Development
Business
Expansion
Docs, Ops
Legal and IP
Global
Franchising
Solution
for big franchisors
Entrepreneur
Services
It can be presumed that in order to secure your investment, it is advisable and secure to put it in the franchising paradigm in order to smoothen out their procedures and set themselves up for following the stage post the pandemic. The best thing is to concentrate on a well-researched and an improved methodology. Certain parameters that definitely need to be worked upon can be broadly categorized as, franchise marketing strategy, lead generation activity and franchise recruitment process.
Here is a framework of 10 ideas that should be kept in mind while developing a plan for the post-pandemic market, which will aid the profit maximization of their businesses.
To start with, organizations can investigate their business income for a couple of months and draw conclusions to comprehend what item and administration will be more sought-after post the lockdown.
A point by point correlation of the product offering and highlights with their rivals can help in better market position.
Alongside that, it is the ideal time to deal with any redevelopment on their products, arrangement and administrations to serve purchasers better.
A digitalized arrangement for their business will assist them with easing their whole business to the executives remotely to defeat any circumstances of manual contact, since the fear will take time to go away from the minds of the consumers.
Retailers from any segment can think of new deals, techniques, and procedures which will without a doubt help them to reach towards the focus of the market again and thus would balance out their income. Thereby, adding to the nation’s economy.
According to the present circumstance, each business needs to comprehend its item stock required to fulfill clients’ necessities, which can be done after studying the need pattern during the time of the pandemic.
Additionally, this circumstance had led to a scenario of segregation and social separation therefore, entrepreneurs can take a shot at remote work processes and activity set up for their representatives, where such conditions would never be an obstacle for your business continuation. This augurs very well for franchises who could work remotely for franchisors. Hence you may start planning a work from home franchise models, or remote sales representative franchises who would market your products or services in your regions.
Appropriately prepare and furnish representatives with accreditations and apparatuses that can assist the business with growing.
A steady correspondence through call, message and email with customers and shoppers on the awareness and vigilance front will assist with reinforcing the business relationship.
Cross working of organizations would be the best methodology to concentrate on since mergers truly work best during any market crisis.
Also, COVID-19 spreads because of human contact and one thing that can be associated with us is manual monetary exchanges. India has around INR 25,000 crore of money dissemination. How sure would we say we are, the cash which you have gotten from somebody has not been tainted? Subsequently now it’s an ideal opportunity to go computerized and begin paying through portable wallets, applications or any bank application to the merchant accomplices. This would give the customers a sense of assurance and security after having faced a pandemic of this level. In contemporary times, digital financing cannot be a secondary choice, it must be our first alternative. This utilization of computerized installment should be rehearsed in all types of cities, tier I, tier II and tier III apart from metropolitan hubs.
Apart from this, it is also imperative to prepare a blueprint and devise a mechanism to not only sustain but also expand the franchises. In order to achieve this, the primary prerogative is to work on the improvement of the franchise as a whole and work on franchise training programs.
Thus, it can be deduced from this
historical economic pattern that the onset of a worldwide pandemic like
COVID-19 would change the overall course of business structure. And it is
therefore the need of the hour to study and analyses the patterns of shifts in
consumer behavior and alter the business plans of your company likewise. Most
Franchisors and Franchises will have to undergo a complete transformation of
how businesses are conducted post this pandemic and hence as a fresh
franchisor, you have great advantage in creating the firsts for your industry
and taking complete advantage of being the first mover.
JITO JBN to host Sparkleminds and FranchiseBazar.com founder and CEO Mr. Amit Nahar at a Mega National Networking Event JBN 360 on 14th and 15th of December 2019 at Sheraton Grand, Bangalore.
The event aims to provide a common platform to meet and connect every stakeholder enthusiastic about new business opportunities in India.
The session will begin with a Masterclass by Mr. Amit Nahar on how to franchise a business covering everything you need to know about expanding your business via the franchise model including the do’s and don’ts when looking to expand your business followed by a panel discussion which will revolve around how entrepreneurs can make the most from the franchise opportunities in some of the top business segments in India.
The discussion will be attended by the key personnel from various brands making the most out of their franchise expansion strategy who will be pointing out some crucial suggestions that these brands would have for entrepreneurs from their segments.
The Panellists would also be shedding light on their successful franchises and what they look in entrepreneurs giving the audience an insight into what it takes to buy a successful franchise and how they can benefit from it.
The session will be held at Sheraton Grand, Bengaluru on Saturday, 14 Dec 2019 from 12.00 PM to 1:15 PM and would witness the presence of Mr. Amol Arora, VC & MD OF SHEMROCK & SHEMFORD Group of Schools, Mr. George K G, Sr. Vice President – Retail, at TTK – Prestige Limited, and Mr. Parag Dutta, Founder and CEO at Roadster Hospitality Private Limited, Mr Sunil Menon, Vice President, Lenskart along with Mr. Amit Nahar.
Each of these Panelists have appointed over 500+ Franchises and have tremendous experience in the franchising industry of India. They will throw light on the challenges they face and how to build a model that can be successful and scaleable.